What is SIF? Full Form, Meaning, Benefits & How Does It Work?
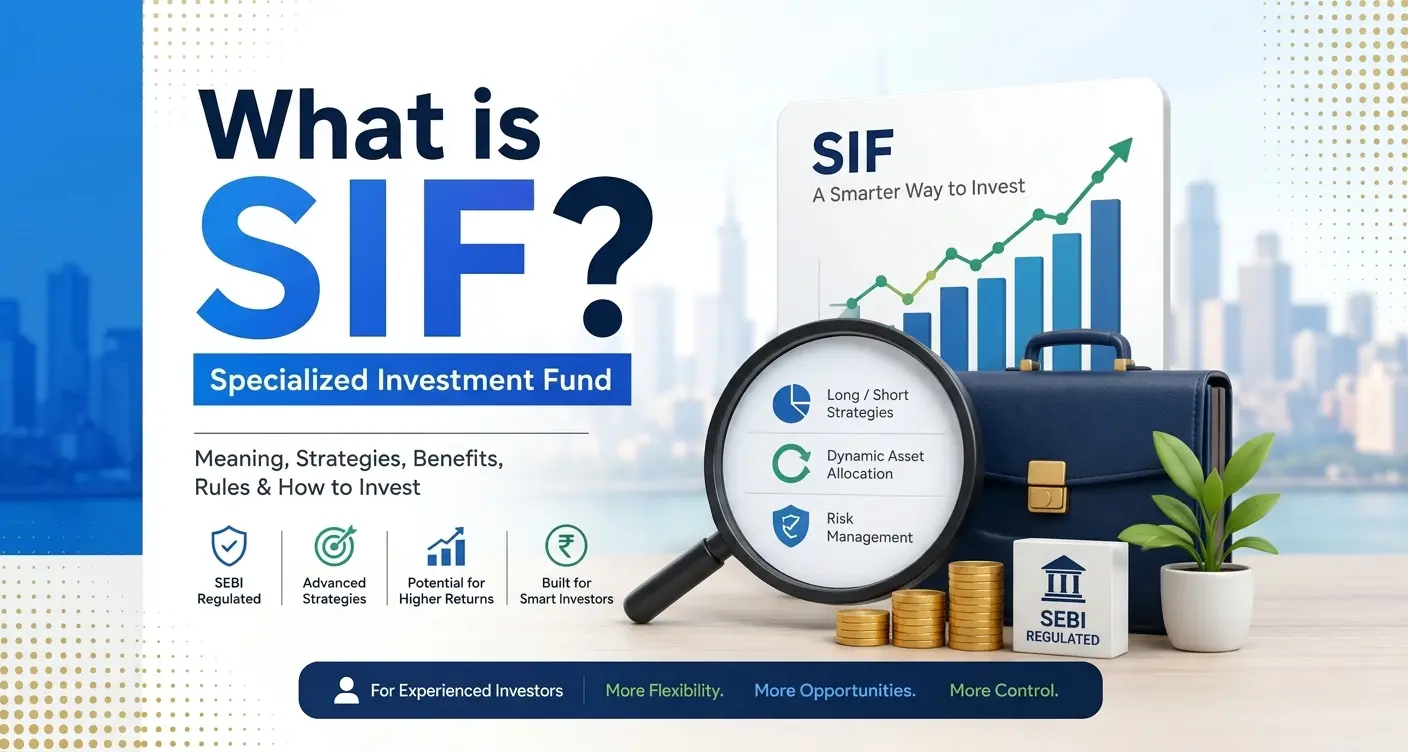
The full form of SIF is Specialized Investment Fund.
If you have been investing in mutual funds for a while, you might have noticed a new term suddenly popping up everywhere. It is not just another fancy acronym created by fund houses. The market regulator, SEBI, actually tore up the old rulebook to create this entirely new category. But what exactly is a SIF? Do you need it? And more importantly, is your money safe in it?
Let us break down what SIF means in simple terms, with no confusing financial jargon. Just the exact facts, SEBI rules, and the reality checks you need before investing a single rupee.
Key Takeaways
- A Specialized Investment Fund (SIF) is a new SEBI-regulated investment category effective from April 1, 2025.
- SIFs bridge the gap between traditional mutual funds and Portfolio Management Services by offering advanced strategies like long-short investing and dynamic asset allocation.
- The minimum investment requirement is strictly Rs 10 lakh per investor, calculated at the PAN level across all SIF strategies of a single AMC.
- SIFs operate under a dedicated regulatory framework dated February 27, 2025, allowing fund managers to take unhedged short exposure of up to 25 percent of net assets.
- These funds can invest across multiple asset classes, including equities, debt instruments, REITs, InvITs, and commodity derivatives.
- SIFs suit experienced investors, High-Net-Worth Individuals, and those seeking opportunities beyond traditional mutual funds.
Table of Contents
Click to Expand
- What is SIF? (Specialized Investment Fund Meaning)
- Why Did SEBI Introduce SIF?
- The Ground Rules: SEBI Regulations and Eligibility
- What Makes SIF Different from Mutual Funds?
- Types of SIF Strategies in India
- Real-World Examples and Vestbox Data
- Benefits of Investing in SIFs
- SIF vs Mutual Fund vs PMS vs AIF
- How is SIF Taxed in India?
- The Risk Matrix: Why SIF is Not for Everyone
- Things to Consider Before Investing
- Who Should Actually Invest in a SIF?
- How Much Should You Actually Invest?
- How to Invest in a SIF in India
- Frequently Asked Questions (FAQs)
What is SIF? (Specialized Investment Fund Meaning)
SIF stands for Specialized Investment Fund. A Specialized Investment Fund (SIF) is a highly advanced category of mutual funds introduced by SEBI. It is designed for modern investors who want the flexibility of Portfolio Management Services, such as short selling and dynamic asset allocation, but want the lower entry barrier and strict regulatory safety of a mutual fund.
Understanding the Specialized Investment Fund (SIF) is crucial because it changes how high-net-worth individuals approach the market. It is not a standard equity fund. It is a strategy-driven vehicle built for specific market conditions.
Why Did SEBI Introduce SIF?
To understand SIF, you need to understand the problem SEBI was trying to solve.
Until recently, Indian mutual funds were confined to strict boxes. A large-cap fund could only buy large-cap stocks. A debt fund could only buy bonds. If a fund manager spotted a brilliant opportunity in a smaller company or wanted to protect the portfolio by betting against a bad stock, they had no option.
On the other side of the fence, Portfolio Management Services and Alternative Investment (AIF) Funds offered this flexibility. But the entry ticket was massive, usually Rs 50 lakh to Rs 1 crore. Many investors jump straight to AIFs, thinking higher fees guarantee better returns, but that is a trap. While these vehicles share similarities, the structural differences are massive. To understand why blindly choosing an AIF over a SIF is a costly mistake, explore our detailed page on SIF vs AIF differences for investors.
Mutual funds were too rigid. PMS was too expensive.
To bridge this gap, SEBI introduced the Specialized Investment Fund (SIF) framework through a dedicated circular dated February 27, 2025, which officially took effect on April 1, 2025. Think of SIF as an open playground for experienced fund managers. It lets them use advanced strategies while keeping the regulatory safety of a mutual fund.
The Ground Rules: SEBI Regulations and Eligibility
SEBI did not just launch SIF and walk away. They put strict safeguards in place to ensure only serious players and serious investors enter this space.
Who Can Launch a SIF?
Not every mutual fund house can launch a SIF overnight. SEBI mandates strict eligibility under two routes:
- Route 1 (Track Record): The AMC must have been in business for at least 3 years with an average Assets Under Management of Rs 10,000 crore. They must have a clean record with no regulatory actions against them in the last 3 years.
- Route 2 (Expert Team): If the AMC lacks the massive AUM, they must hire a dedicated Chief Investment Officer with at least 10 years of experience managing Rs 5,000 crore or more, along with a co-fund manager with 3 years of experience.
The Rs 10 Lakh Minimum Investment Rule
You cannot start a Rs 500 SIP in an SIF. SEBI has set a strict minimum investment threshold of Rs 10 lakh per investor.
Here is the catch: This Rs 10 lakh is calculated at the PAN level across all SIF strategies of a single AMC. If you invest Rs 6 lakh in one SIF strategy of an AMC, you cannot invest just Rs 4 lakh in its second SIF strategy. You must invest another Rs 10 lakh. However, this minimum investment requirement does not apply to accredited investors.
Active and Passive Threshold Breaches:
To prevent investor-initiated redemptions from reducing the overall SIF investment below Rs 10 lakh, the AMC must monitor investor holdings daily. If an investor tries to redeem an amount that would drop their SIF value below Rs 10 lakh, it is an active breach and is not permitted.
However, if the investment value drops below Rs 10 lakh solely due to a decline in NAV or market movements, it is considered a passive breach rather than a regulatory violation. In a passive breach, the investor cannot make partial redemptions and can redeem only the entire remaining SIF investment.
What Makes SIF Different from Mutual Funds?
An equity fund plays only one side of the game: buying good stocks and hoping they go up. A SIF plays both sides.
The Power of “Unhedged Shorting”
In a mutual fund, fund managers can use derivatives only to protect their existing investments. A SIF can use derivatives to generate active returns. SEBI allows SIFs to take an unhedged short exposure of up to 25 percent of their net assets.
In simple terms, an SIF manager can legally bet against a stock they think will crash, without owning it. If the stock falls, the SIF profits. This is a game changer for Indian retail investors.
If terms like unhedged shorting or derivatives sound complex, do not worry. We have broken down the exact mechanics. To understand how fund managers execute these strategies, read our guide on SIF strategies: how long-short arbitrage & derivatives work in SIFs.
Types of SIF Strategies in India
Because SIF is a broad category, SEBI has permitted very specific strategies under it. If you are looking at a SIF, it will likely fall into one of these buckets:
Equity-Oriented SIFs
- Equity Long Short Funds: The fund buys good stocks and bets against bad stocks. Minimum 80 percent must be in equity.
- Equity Ex Top 100 Long Short Funds: These funds ignore the giant top 100 companies. They hunt for opportunities in mid-cap and small-cap stocks, using shorting to manage risk. At least 65 percent must be in equity outside the top 100.
- Sector Rotation Long Short Funds: The manager picks up to 4 specific sectors and rotates capital between them. They can even short entire sectors if they think one is about to decline.
Debt-Oriented SIFs
- Debt Long-Short Funds: These funds trade interest rate movements and bond prices using debt derivatives.
- Sectoral Debt Long Short Funds: These funds invest in debt instruments from at least two sectors, with a maximum 75 percent limit in any single sector to avoid concentration.
Hybrid SIFs
- Active Asset Allocator Long Short Funds: The most flexible category. The manager can dynamically allocate capital across equity, debt, REITs, InvITs, and even commodity derivatives based on where the best opportunities exist.
- Hybrid Long Short Funds: Must keep at least 25 percent in equity and 25 percent in debt at all times, but can use shorting around these core holdings. These are usually structured as Interval Funds.
Real-World Examples and Vestbox Data
To ground this in reality, consider the data. Based on Vestbox data, funds using unhedged shorting during market corrections saw drawdowns limited to a percentage, while traditional equity funds lost some percentage. This proves the structural advantage of SIFs during volatility.
A few examples of SIFs that have recently hit the Indian market include:
- Zerodha Fund House WSIF Equity Long-Short Fund: An open-ended fund focusing exclusively on the equity long-short strategy. On their platform, it carries a "Very High Risk" label.
- SBI Magnum SIF: SBI has launched multiple strategies under this, including an "Active Asset Allocator Long-Short Fund" that targets a mix of 65–75% equity/arbitrage, 25–35% fixed income, and 0–10% in REITs/InvITs.
- Quantum Qsif Equity Long Short Fund: Another example of an AMC utilising the pure equity long-short framework permitted by SEBI.
Benefits of Investing in SIFs
Specialised Investment Funds offer several distinct advantages for investors looking to step beyond traditional mutual funds:
- Access to Advanced Strategies: SIFs allow fund managers to use a wider range of investment strategies, enabling them to identify opportunities across different market conditions and asset classes.
- Greater Portfolio Flexibility: Fund managers can adjust allocations in response to market opportunities and risks without being tied to strict mutual fund mandates.
- Multi-Asset Diversification: Depending on the strategy, SIFs can invest across equities, debt instruments, REITs, InvITs, and commodity derivatives, which helps reduce concentration risk.
- Regulated Transparency: Because SIFs operate under SEBI mutual fund regulations, investors benefit from mandatory daily NAV calculations, strict disclosure norms, and comprehensive risk-management requirements.
- Lower Entry Barrier: SIFs offer institutional-level strategies without requiring the massive Rs 50 lakh to Rs 1 crore ticket size associated with PMS or AIFs.
SIF vs Mutual Fund vs PMS vs AIF
Let us clear up the confusion. Here is how SIF stacks up against your other options:
| Feature | Mutual Fund | Specialized Investment Fund (SIF) | Portfolio Management Service (PMS) | Alternative Investment Fund (AIF) |
|---|---|---|---|---|
| Minimum Investment | As low as Rs 500 | Rs 10 Lakh (PAN level) | Rs 50 Lakh | Rs 1 Crore+ |
| Flexibility | Low (Strict category limits) | High (Can short, multi asset) | Very High (Customized) | Extremely High |
| Use of Derivatives | Only for hedging | For profit (Up to 25% unhedged) | Unrestricted | Unrestricted |
| Liquidity | High (Daily withdrawal) | Moderate (Intervals/notice periods) | Moderate (Notice periods) | Low (Locked-in for years) |
| Regulation | SEBI MF Regulations | SEBI MF Regulations + SIF Framework | SEBI PMS Regulations | SEBI AIF Regulations |
This table is just the surface-level view. The actual fee structures, lock-in periods, and tax treatments vary significantly among these four options. Choosing the wrong structure can cost you lakhs in hidden charges over the years. See the detailed mathematical breakdown of SIF vs PMS vs AIF vs Mutual Funds.
How is SIF Taxed in India?
Taxation is where many investors get confused. SIF taxation does not depend on the fund name. Under the Income Tax Act, taxation depends entirely on the fund's average daily holdings.
Rule 1: The 65% Equity Test
If the SIF maintains an average of 65 percent or more of its money in Indian equity shares, it is treated as an Equity-Oriented Fund for tax purposes.
- Short-Term Capital Gains: If you sell within 12 months, you pay a flat 20 percent tax under Section 111A.
- Long-Term Capital Gains: If you sell after 12 months, gains up to Rs 1.25 lakh per year are tax-free. Anything above that is taxed at 12.5 percent.
Rule 2: The Debt Trap
If the SIF invests less than 65 percent in equities, it is taxed as a Debt Fund.
- As per the rules set after April 1, 2023, all gains from debt funds are added to your total income and taxed at your personal income tax slab rate. There is no indexation benefit.
Tax rules become highly complex when derivatives are involved. To understand the complete math behind SIF taxation and fee structures, check our comprehensive guide on SIF Taxation and fee structures.
The Risk Matrix: Why SIF is Not for Everyone
We will not sugarcoat this. SIFs are powerful, but they carry sharp edges.
- Derivatives Risk: If a SIF manager takes a 25 percent unhedged short position and the market suddenly rallies rather than falling, those derivative positions will incur significant losses.
- Liquidity Risk: Unlike mutual funds, many SIFs are Interval Funds. You can only redeem your units during specific windows. Even open-ended SIFs can require a notice period of up to 15 working days before you receive your money.
- Manager Risk: A regular index fund does not need a genius manager. A SIF relies heavily on the fund manager's skill to place the right long and short bets. If the manager is wrong, your Rs 10 lakh could lose significant value.
- Concentration Risk: Strategies like Sector Rotation can still concentrate your money heavily into just 3 or 4 sectors, making you highly vulnerable to sector-specific news.
These risks sound theoretical until you see real numbers in a falling market. If you want to see historical data on it, SIFs require a different mindset. Explore the truth about SIF returns, volatility, drawdowns, and crashes.
Things to Consider Before Investing
Before putting your money into a Specialized Investment Fund, evaluate these critical factors:
- Investment Objective: Make sure the fund strategy aligns with your financial goals and investment horizon.
- Risk Appetite: SIFs use advanced strategies and carry higher risk than traditional mutual funds. Invest only if you are completely comfortable with market volatility.
- Liquidity Needs: Check the redemption frequency. Some SIFs have weekly, monthly, or other periodic redemption windows, which could unexpectedly lock up your capital.
- Fund Manager Experience: Because SIFs involve highly active portfolio management, the fund management team's expertise and track record are paramount.
- Costs and Expenses: Review the expense ratio and any other associated charges. Complex strategies often come with higher management fees.
Who Should Actually Invest in a SIF?
Be brutally honest with yourself before looking at SIFs. You should only consider this if:
- You have a fully funded emergency fund.
- You already have a solid core portfolio of mutual funds.
- You have at least Rs 10 lakh in surplus funds you can lock away without needing them urgently.
- You understand that the fund manager will use Futures and Options, and you are comfortable with that level of risk.
Who should avoid it?
If you are still building your core wealth, or if you panic seeing red numbers in your portfolio during a volatile month, stay miles away from SIFs. Stick to simple equity mutual funds.
How Much Should You Actually Invest?
Let us say you tick all the boxes above and have a Rs 10 lakh surplus. The biggest mistake HNIs make is putting their entire amount into a single SIF strategy just because they can. A SIF is a satellite investment, not your core portfolio.
To determine the exact percentage of your wealth to allocate, explore our recommended SIF Portfolio Allocation.
How to Invest in a SIF in India
If you tick all the boxes above, here is how you invest:
- Choose the Right Strategy: Decide whether you want an Equity Long-Short or a Multi-Asset Allocator based on your market view.
- Check the AMC Eligibility: Ensure the fund house meets SEBI's strict AUM or CIO experience criteria.
- Read the Fine Print: Look specifically for the exit load, redemption window, and withdrawal notice period.
- Execute the Transaction: You can invest directly in Specialized Investment Funds via the Vestbox web platform or via the Vestbox Smartphone App. Ensure your KYC is registered with the KRA and your Aadhaar and PAN are linked.
- Monitor Actively: Check the SIF bi-monthly portfolio disclosures to see what long and short positions the manager is taking.
Before you write the cheque, don't rely only on the fund house marketing pitch. Use our step-by-step checklist on how to choose the right SIF.
If you have done your due diligence and are ready to add this advanced asset class to your portfolio, Vestbox has curated a list of SEBI-approved SIFs that meet strict quality checks.
Frequently Asked Questions (FAQs)
What does SIF stand for?
SIF stands for Specialized Investment Fund.
What does SIF mean in mutual funds?
In mutual funds, SIF refers to a SEBI-regulated investment category that offers more flexible and specialised investment strategies than traditional mutual funds. It allows fund managers to take unhedged short positions.
Does SEBI regulate SIF?
Yes, SIFs operate under a dedicated regulatory framework that SEBI introduced through a circular dated February 27, 2025, effective from April 1, 2025.
What is the minimum investment in SIF?
The minimum investment requirement for a SIF is Rs 10 lakh across all SIF strategies offered by the same AMC, calculated at the PAN level.
How is SIF taxed?
SIF taxation depends on its underlying asset allocation. If it holds 65 percent or more in equities, it is taxed as an equity fund. If not, it is taxed according to the applicable debt mutual fund tax rules.
What is the difference between SIF and PMS?
A SIF pools money from multiple investors under a mutual fund structure, while a PMS provides customised portfolio management for individual investors and requires a minimum investment of Rs 50 lakh.
Are SIFs good for beginners?
No. SIFs are generally intended for experienced investors and may not suit beginners because they use derivatives and concentrated strategies.
Can NRIs invest in SIFs?
NRI participation depends on the AMC's policies and applicable regulatory guidelines. They must ensure their PAN and KYC are fully compliant.
Ready to explore?
SEBI-regulated long-short and hedging strategies designed to capture opportunities in all market conditions.
Disclaimer
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Please consult a certified financial advisor before making any investment decisions.
Trust & Compliance
This article has been created following our strict Editorial Policy. We believe in complete transparency regarding how we operate; you can read our Disclosures. For legal liabilities and risk factors, please review our Disclaimer.
Share & Save Article
Other Posts
What is ESOP? A Complete Guide to Employee Stock Ownership Plans
Aug 6, 2026
ESOP Taxation in India: A Complete Guide to Perquisite & Capital Gains Tax
Aug 7, 2026
ESOP vs Equity Shares vs RSU: Understanding Employee Equity
Aug 11, 2026
ESOP vs ESPP: Which Employee Equity Plan is Better?
Aug 11, 2026
