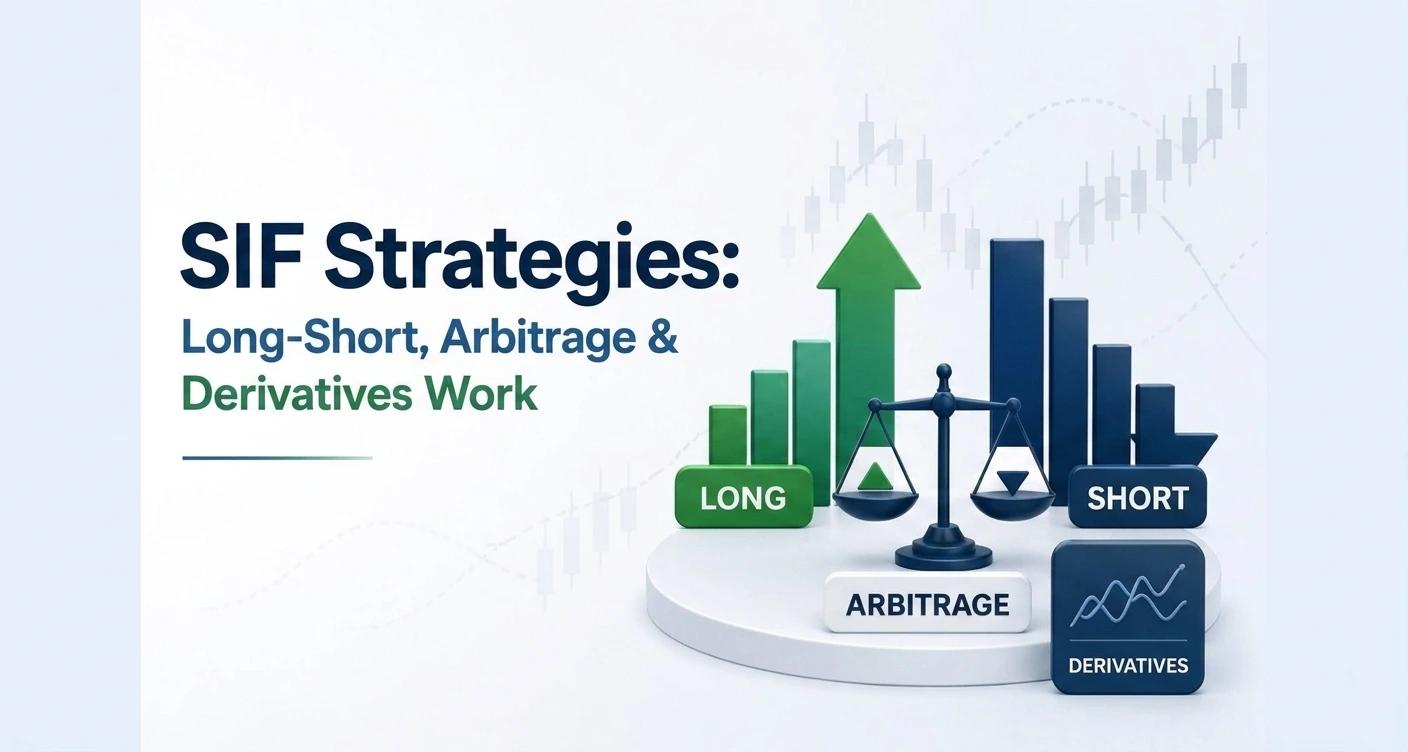
Decoding SIF Strategies: How Long-Short, Arbitrage & Derivatives Work
Stop using the word "Alpha" if you mean high returns.
Buying a small-cap stock right before a rally and making 30 percent is not alpha. That is just taking more risk and getting lucky. True alpha generates returns with zero correlation to the Nifty 50. It is making money when the market is flat. It is protecting capital when the market is bleeding.
To invest in SIF strategies, first understand how elite fund managers manufacture returns using pure mathematics, not market momentum. If you need a primer on the vehicle itself, read our guide on What is SIF Funds? How do SIFs work?.
Let's break down the three primary engines that power Specialized Investment Funds.
Key Takeaways
- SIF strategies aim to generate absolute returns uncorrelated with the broader stock market.
- Long-Short equity strategies buy high-conviction stocks while simultaneously shorting weak stocks to neutralize market risk.
- Market-neutral arbitrage exploits pricing inefficiencies between cash and futures markets to generate steady returns.
- Delta-Neutral strategies use complex options trading to profit from volatility and human fear rather than market direction.
- Unlike standard mutual funds, SIFs can legally use derivatives for purposes other than hedging.
Table of Contents
Click to Expand
Long-Short Equity: The Offensive Shield
This is the most common and intuitive architecture in the SIF space. It is designed for investors who want to participate in the upside of the Indian growth story but refuse to accept the full downside of a crash.
The Mechanics
The fund manager identifies a high-conviction theme, say, India's transition to electric vehicles. They go long by buying top-tier battery manufacturers. But they do not stop there.
To mathematically neutralize sector risk, they simultaneously go Short by selling legacy auto companies that are losing market share.
If the broader auto sector declines due to a global supply chain disruption, your long positions take a hit. But your short positions surge in value, acting as an airbag. You are hedged.
The Vestbox Reality
During a recent sharp decline in the IT sector because of global banking fears, standard IT mutual funds fell sharply. However, according to Vestbox data, SIFs running paired long-short IT strategies limited their drawdowns to an estimated fraction of the index.
They shorted fundamentally weak IT service providers, offsetting losses in their strong core holdings.
The Regulatory Wall
Why does your standard mutual fund not do this?
Under the SEBI (Mutual Funds) Regulations, 1996, standard equity schemes must remain long-only. You can verify this in the SEBI Mutual Funds Regulations, 1996.
They are legally prohibited from holding short positions or writing derivatives for pure profit.
Market-Neutral Arbitrage: Extracting the Spread
Arbitrage is the closest thing to a mathematical free lunch in finance. It doesn't care whether the Nifty goes up, down, or sideways. It cares only about pricing inefficiencies between two linked markets.
The Mechanics
In the Indian stock market, the futures price of a stock is almost always slightly higher than its cash market price. This difference is called the contango.
An arbitrage SIF will buy Reliance in the cash market at Rs 2,500 and simultaneously sell its futures contract at Rs 2,520. When the contract expires, the cash and futures prices must perfectly merge. The fund pockets that Rs 20 risk-free.
Multiply this across thousands of crores of capital and dozens of stocks, and it generates a steady return similar to a bank FD.
The Retail Trap
If this strategy is so easy, why don't retail investors do it?
Because of friction. Brokerage charges, Securities Transaction Tax, and slippage eat up that Rs 20 profit for a retail trader.
SIFs operate at the institutional scale. Based on Vestbox data, algorithmic execution models show that by negotiating near-zero brokerage and using high-frequency servers to eliminate slippage, an institutional arbitrage SIF can capture these microscopic spreads and compound them into an estimated 8 to 9 percent annualized return, completely insulated from market crashes.
Delta-Neutral Strategies: Getting Paid for Volatility
This is the most advanced and aggressive method in SIF. It is not for beginners.
Delta-neutral funds do not bet on stock prices. They bet on human psychology and fear.
The Mechanics
In options trading, delta measures how much an option's price changes for every unit move in the underlying stock.
A delta-neutral manager buys and sells a complex web of call and put options so their net exposure to market direction is exactly zero.
Why do this?
Because when people panic, options get insanely expensive. The SIF acts as the insurance company. They construct strategies like Iron Condors that allow them to collect a massive upfront premium.
As long as the market stays within a predictable wide range, the options expire worthless, and the SIF keeps the premium as pure profit.
The Brutal Reality
Delta-neutral is psychologically brutal to manage. If a sudden Black Swan event occurs, like a surprise geopolitical conflict, the market gaps down violently.
The insurance the SIF sold suddenly becomes a massive liability. The manager must aggressively buy back options at a loss to reset their delta to zero.
Surviving sudden market gaps requires supercomputers and split-second execution.
High Conviction vs. Diversified SIFs
How a fund manager applies these strategies depends entirely on their philosophy:
High Conviction SIFs
The manager runs a highly concentrated portfolio of 15 to 20 stocks. The long and short hedges are aggressive. The potential for massive alpha is high, but the stock-picking risk is elevated.
Diversified SIFs
The manager runs a broader portfolio of 60 to 80 stocks. They use derivatives to manage the overall beta or market exposure. The returns are smoother and more predictable.
To understand how to size these different strategies within your overall wealth, read our guide on SIF Portfolio Allocation.
The True Role of Derivatives in SIF Portfolios
Retail investors use derivatives to gamble on direction. Institutional SIF managers use derivatives as surgical tools to transfer risk from your portfolio to someone else.
They do not buy options hoping the market crashes so they get rich. They buy options to ensure that if the market crashes, their equity capital remains intact.
A standard mutual fund manager is essentially driving a car with no brakes, hoping the road stays smooth forever. A SIF manager installs aerospace-grade braking systems to navigate tight turns at high speeds.
To see how this structural advantage compares against other wealth vehicles, read our breakdown on SIF vs PMS vs Mutual Funds.
Before you invest, you must also understand the tax implications, which you can explore in our guide on SIF Taxation.
If you are still trusting your wealth to a vehicle without brakes, it is time to upgrade your architecture.
Disclaimer: The performance figures and scenarios above are illustrative, based on expected market behavior and estimated Vestbox data. The figures are approximate and meant strictly for educational purposes to demonstrate strategy mechanics. Actual market returns and fund performance will vary based on real-time conditions.
Frequently Asked Questions
What are the main SIF strategies?
The primary SIF strategies are Long-Short Equity, Market-Neutral Arbitrage, and Delta-Neutral options trading. These strategies use derivatives to generate returns uncorrelated to the broader stock market.
How does a Long-Short SIF strategy work?
A Long-Short strategy buys high-conviction stocks while simultaneously shorting weak stocks in the same sector. This neutralizes market risk, allowing the fund to profit from the relative stock performance rather than the market direction.
Can SIFs use derivatives for profit?
Yes. Under the SEBI SIF circular dated February 27, 2025, SIFs can take unhedged short exposure of up to 25 percent of their net assets. Unlike standard mutual funds, SIFs can use derivatives to generate active returns, not just for hedging.
You can verify the framework in SEBI’s SIF Circular February 2025.
Is SIF arbitrage risk-free?
While arbitrage exploits risk-free pricing spreads, it is not entirely risk-free. The fund remains exposed to execution risk, slippage, and liquidity gaps during extreme volatility.
However, it is structurally much safer than directional equity investing.
What is a Delta-Neutral SIF?
A Delta-Neutral SIF uses complex options strategies like Iron Condors to collect premium income. The fund maintains net-zero exposure to market direction, profiting from volatility and time decay rather than a rising stock market.
Are SIF strategies better than mutual funds?
SIF strategies offer institutional-grade downside protection that standard mutual funds cannot provide. However, they involve complex derivative risks.
They suit HNIs seeking market-independent alpha, while mutual funds remain better suited to core long-term compounding.
Want the full overview of SIFs, regulations, and benefits? Explore the complete guide to What are Specialized Investment Funds (SIFs)? How do SIFs work?
Ready to explore?
SEBI-regulated long-short and hedging strategies designed to capture opportunities in all market conditions.
Disclaimer
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Please consult a certified financial advisor before making any investment decisions.
Trust & Compliance
This article has been created following our strict Editorial Policy. We believe in complete transparency regarding how we operate; you can read our Disclosures. For legal liabilities and risk factors, please review our Disclaimer.
Share & Save Article
Other Posts
What is ESOP? A Complete Guide to Employee Stock Ownership Plans
Aug 6, 2026
ESOP Taxation in India: A Complete Guide to Perquisite & Capital Gains Tax
Aug 7, 2026
ESOP vs Equity Shares vs RSU: Understanding Employee Equity
Aug 11, 2026
ESOP vs ESPP: Which Employee Equity Plan is Better?
Aug 11, 2026
