SIF vs PMS vs Mutual Fund: Difference, Benefits, Risks, Taxation & Minimum Investment
Let us settle this once and for all.
If you have a Rs 10 Lakh to Rs 5 Crore corpus, the Indian wealth management industry wants to fragment your attention. They tell you to use Mutual Funds for safety, PMS for prestige and exclusivity.
It is exhausting. It fractures your portfolio visibility. And mostly, it is a structural mismatch between what your wealth actually requires in a hyper-connected, volatile global economy and what the industry is legally allowed to sell you.
To see the full SIF vs Mutual Fund vs PMS breakdown, stop reading marketing brochures and start reading the legal rulebooks that govern your money. Let’s rip the cover off India’s four major wealth structures.
Key Takeaways
**
- Mutual funds offer low entry barriers but are restricted to long-only strategies and strict SEBI category mandates.
- PMS provides high flexibility and concentrated bets but requires a minimum investment of Rs 50 lakh and operates with low transparency.
- SIFs bridge the gap by offering derivative flexibility and daily NAV transparency with a Rs 10 lakh entry point.
- A Specialized Investment Fund sits in the Goldilocks zone, providing institutional-grade downside protection without the PMS entry tax.
Table of Contents
Click to Expand
- The Structural Boundaries of Mutual Funds
- PMS: The Rs 50 Lakh Customization Tax
- SIF vs Direct Equity and Index Investing
- SIF vs PMS vs Mutual Fund: The Definitive Comparison Matrix
- The Vestbox Case Study: Architecting Downside Protection
- The Final Verdict: Should You Switch?
- Frequently Asked Questions
The Structural Boundaries of Standard Mutual Funds
Do not misunderstand: mutual funds are arguably the greatest financial invention for wealth creation. However, for a high-net-worth investor building a modern, resilient portfolio, standard mutual funds operate within strict structural boundaries.
Under the SEBI (Mutual Funds) Regulations, 1996, an equity fund is defined by its mandate from inception. If it is categorized as a Large Cap fund, the manager must hold at least 80 percent of the fund's assets in the top 100 stocks. You can verify the exact categorization norms through the SEBI Mutual Funds Regulations 1996.
This structure is perfect for steady, long-term compounding, but it means the fund inherently inherits the market downside. If the broader market drops 20 percent, your fund will closely follow. Why? Because the manager toolkit is intentionally limited.
To maintain category purity, they cannot hold significant cash to defend against corrections. They cannot use derivatives to hedge their positions, nor can they short sell an overvalued stock. You pay a management fee for excellent stock selection, but the manager is fundamentally restricted to a long-only approach during a market crash.
The Myth vs. The Reality
- Myth: My mutual fund manager will move my money to cash if they see a crash coming.
- Reality: If a Large-Cap manager suddenly exits stocks to hold cash to dodge a correction, SEBI will flag them for style drift and penalize the AMC. Their regulatory mandate is not to protect your downside. It is to stay fully invested in their specific category at all times.
PMS: The Rs 50 Lakh Customization Tax
Portfolio Management Services (PMS) solves the flexibility problem. Under the SEBI (Portfolio Managers) Regulations, 2020, managers can make concentrated bets on 10 to 15 stocks, short sell, and use complex strategies.
But PMS comes with two massive hidden taxes:
- The Entry Barrier: The minimum investment is Rs 50 Lakhs. This immediately locks out a significant segment of experienced investors who have built a Rs 15 Lakh or Rs 20 Lakh corpus but have not yet reached Ultra HNI status.
- The Fee Drain: PMS fee structures are brutal. A typical PMS charges a 2 percent fixed management fee, plus a 20 percent profit-sharing fee on gains above a hurdle rate. If the market does well, the fees eat your alpha. If the market performs poorly, you still pay the 2 percent fixed fee just for them holding your money.
Furthermore, PMS operates as a black box. There is no daily NAV published. You get a monthly statement, but you never really know exactly what your manager is doing each day.
SIF vs Direct Equity and Index Investing
You might ask, why not just manage my own money?
Direct equity investing is great for generating alpha on a small core portfolio. But can you, as an individual, write algorithms to cover calls against your portfolio to extract additional yield? Using futures, can you run cross-sector paris trades that isolate market risk?
No. The infrastructure costs, margin requirements, and screen time make it impossible for a working professional to execute this at scale.
What about Index Funds and passive investing? This is the biggest trap for HNIs. If the market enters a prolonged sideways, volatile cycle, which defines modern macro environments, your wealth literally generates nothing. Index funds are a great tool, but they offer zero defense mechanisms. They only make money when the market goes up.
To understand how these alternative strategies work, read our guide on SIF Strategies: How long-short arbitrage derivatives work.
SIF vs PMS vs Mutual Fund: The Definitive Comparison Matrix
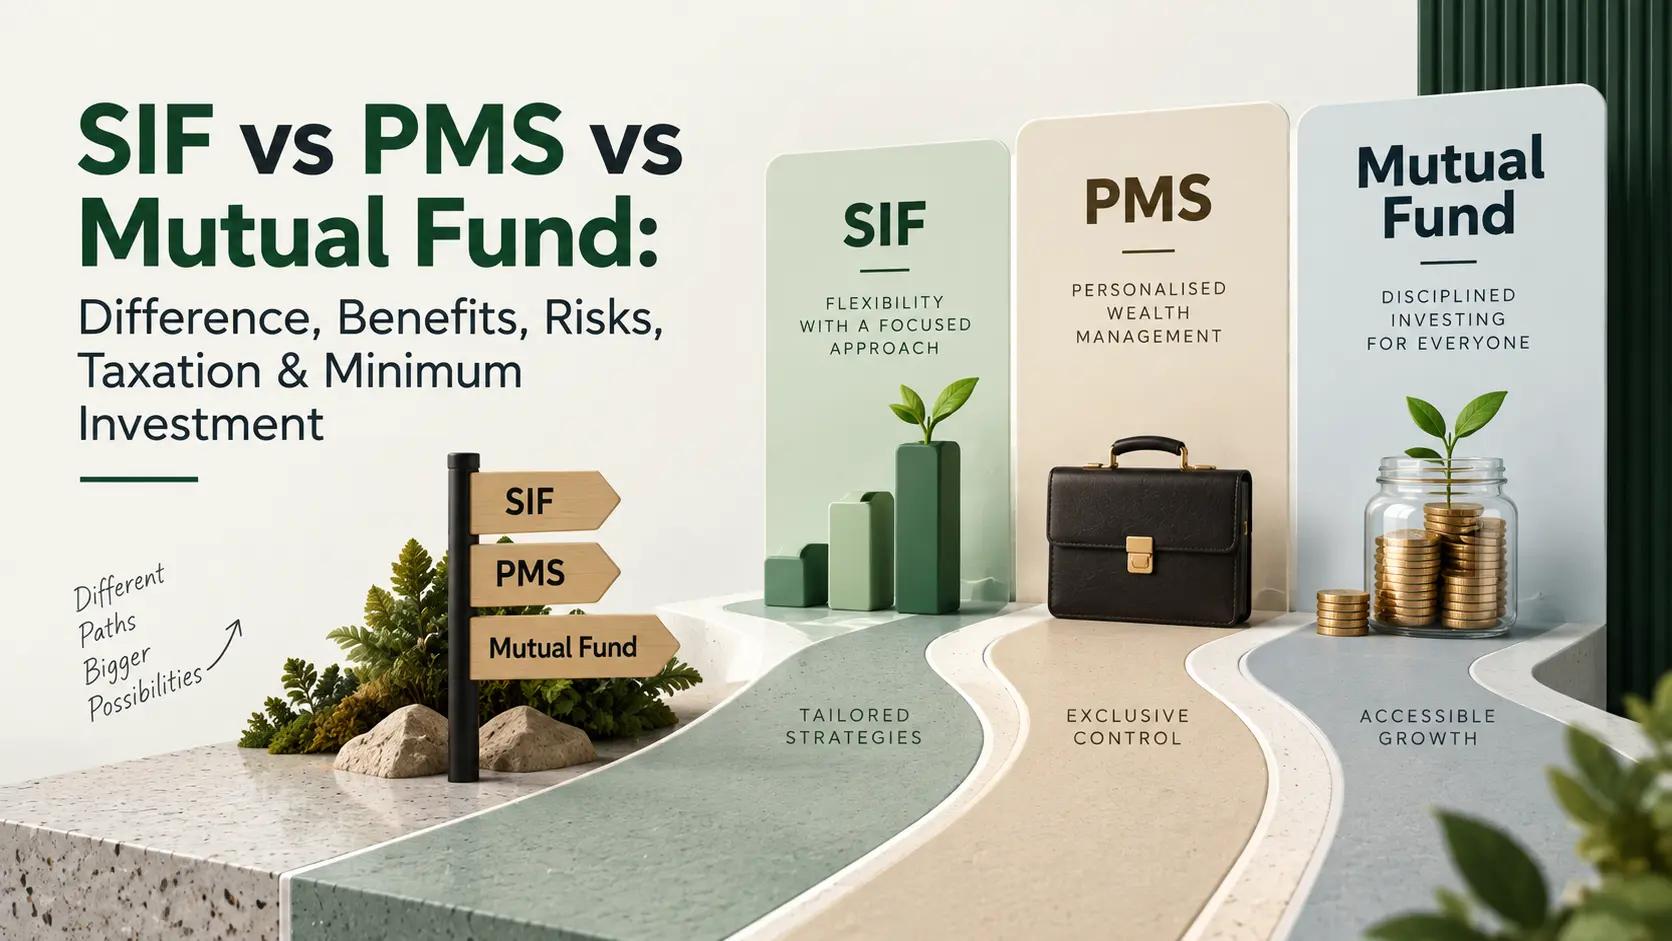
When comparing SIFs, PMSs, and Mutual Funds, the core differences lie in regulation, flexibility, and entry barriers. Mutual funds offer low entry but strict long-only mandates. PMS offers high flexibility but requires Rs 50 lakh and lacks transparency. SIFs bridge the gap by offering derivative flexibility and daily NAV transparency with a Rs 10 lakh entry point.
Here is the exact structural breakdown:
| Feature | Mutual Funds | PMS | Specialized Investment Fund (SIF) |
|---|---|---|---|
| Minimum Investment | Rs 500 to Rs 5,000 | Rs 50 Lakhs | Rs 10 Lakhs |
| Strategy Flexibility | Long Only (Caged) | High (But Black Box) | High (Hedging, Long/Short) |
| Transparency | Daily NAV, Full Disc. | Monthly Statements | Daily NAV, Full Disc. |
| Liquidity | High (T+1/T+2) | Contractual | Structured (T+2 to 30 days) |
| Fee Structure | 1 to 2% TER | 2% + 20% Profit | Standard TER + Perf. Fee |
| Regulatory Framework | SEBI MF Regs 1996 | SEBI PMS Regs 2020 | SEBI MF Regs + SIF Framework |
For a deeper dive into how these structures compare to AIFs, explore our detailed guide on SIF vs AIF differences for investors.
The Vestbox Case Study: Architecting Downside Protection
Let us look at a real-world scenario to see how this plays out in actual rupees, not just theory.
The Client: A 48-year-old surgeon from Mumbai with a total portfolio estimated at Rs 2 Crore.
The Previous Setup: Rs 1 Crore in PMS (concentrated mid-cap equity), Rs 50 Lakhs in Large-Cap Mutual Funds, and Rs 50 Lakhs in FDs.
The Problem: During the last severe mid-cap drawdown cycles, his PMS dropped roughly 28 percent. His mutual funds dropped 18 percent. He lost nearly Rs 37 Lakhs in a matter of months. He had zero downside protection and massive anxiety.
The Vestbox Restructure
- Core: Rs 1 Crore in Index Funds or Mutual Funds (Large-Cap or Mid-Cap Oriented) for long-term India growth.
- Satellite: Rs 50 Lakhs deployed into distinct SIF funds, including a Long-and-Short SIF and a Market Neutral Arbitrage SIF.
- Support: Rs 50 Lakhs deployed into PMS funds for flexibility and concentration.
The Result
When the broader market faced its next major correction, his core mutual funds dropped 12 percent. However, based on Vestbox data, his SIF allocation stayed flat at a positive 0.5 percent thanks to flawless derivative hedging.
Instead of losing Rs 24 Lakhs, his total portfolio drawdown was restricted to just Rs 8.4 Lakhs. He slept peacefully. And because his drawdown was mathematically smaller, he compounded his wealth much faster when the market recovered.
To understand how to size these positions correctly, check our guide on SIF Portfolio Allocation.
Disclaimer: The above scenario is an illustrative study based on expected market behavior and estimated Vestbox data. The figures are approximate and meant strictly for educational purposes to demonstrate portfolio architecture. Actual market returns and fund performance will vary based on real-time conditions.
The Final Verdict: Should You Switch?
SIFs sit in the exact Goldilocks zone of modern Indian investing.
They offer the derivative flexibility and tactical freedom of AIFs and PMS. But they strip away the Rs 50 Lakh entry barrier. They eliminate the 3-year illiquidity lock-ins and resolve the transparency problem by operating within the mutual fund framework, which provides daily NAVs and strict SEBI trustee oversight.
If you want simple market-matching returns, use Index Funds. But if you want tactical, liquid, institutional-grade downside protection without paying the Rs 50 Lakh PMS entry tax, a Specialized Investment Fund is the undisputed champion.
To understand the tax implications before switching to SIFs, read our breakdown on SIF Taxation.
If you are ready to take back control of your downside, explore Vestbox curated SIF investments.
Explore our guide: What Are Specialized Investment Funds (SIFs)?
Frequently Asked Questions
What is the main difference between SIF and PMS?
The main difference between SIFs and PMSs lies in their structure and entry barrier. A SIF requires a minimum of Rs 10 lakh and operates with mutual fund-level transparency. A PMS requires a minimum of Rs 50 lakh and operates as a less transparent, customized portfolio.
Can a SIF replace my mutual fund portfolio?
No. A SIF is designed to be a satellite investment to hedge downside and generate alpha, not a core compounding engine. Use mutual funds for steady long-term growth and SIFs for tactical defense.
Is SIF safer than mutual funds?
SIFs are not necessarily safer, but they manage risk differently. While mutual funds inherit the full market downside during a crash, SIFs can use derivatives to hedge their positions.
However, using derivatives also creates complex risks that standard mutual funds do not face.
What is the minimum investment for SIF vs PMS vs Mutual Fund?
A mutual fund requires a minimum of Rs 100. A Specialized Investment Fund requires a strict minimum of Rs 10 lakh per investor at the PAN level. A Portfolio Management Service requires a strict minimum of Rs 50 lakh.
Are SIFs taxed like mutual funds?
Yes, SIFs are taxed exactly like mutual funds based on their underlying asset allocation. If a SIF holds 65 percent or more in equities, it is taxed under equity taxation rules. If it holds less, it is taxed as a debt fund.
Ready to explore?
SEBI-regulated long-short and hedging strategies designed to capture opportunities in all market conditions.
Disclaimer
Mutual fund investments are subject to market risks. Read all scheme-related documents carefully. Please consult a certified financial advisor before making any investment decisions.
Trust & Compliance
This article has been created following our strict Editorial Policy. We believe in complete transparency regarding how we operate; you can read our Disclosures. For legal liabilities and risk factors, please review our Disclaimer.
Share & Save Article
Other Posts
What is ESOP? A Complete Guide to Employee Stock Ownership Plans
Aug 6, 2026
ESOP Taxation in India: A Complete Guide to Perquisite & Capital Gains Tax
Aug 7, 2026
ESOP vs Equity Shares vs RSU: Understanding Employee Equity
Aug 11, 2026
ESOP vs ESPP: Which Employee Equity Plan is Better?
Aug 11, 2026
